 Ginnie Baker
Explore these year-end charitable giving strategies, from donating appreciated securities and making Qualified Charitable Distributions (QCDs) from IRAs to leveraging Donor-Advised Funds (DAFs), to maximize your tax benefits and stay on top of Required Minimum Distributions (RMDs) before the November 13 deadline.
Now is a good time to consider both the causes you care about and the requirements you must meet before year-end. Thoughtful, timely giving not only helps the charities you care about continue their important work, it can also provide meaningful tax advantages for you and your family. We’re here to guide you through some lesser-known strategies that can help you make the most of your generosity this season.
Below are several strategies to consider as you plan your charitable giving for the remainder of 2026.
Beaird Harris Year-End Gifting Deadline: Friday, November 13
To allow adequate time for processing, please contact us with any charitable gifting requests using the strategies below by Friday, November 13.
1. Gifting Appreciated Securities
Rather than selling appreciated securities you’ve held for more than one year and donating the after-tax proceeds, consider donating the securities directly to a qualified charity.
This strategy may allow you to avoid realizing capital gains on the appreciation while potentially receiving a charitable deduction based on the securities’ fair market value, subject to applicable IRS limitations.
For individuals with highly appreciated investments, gifting securities can be an especially tax-efficient way to support the organizations that matter most to you.
2. Charitable IRA Distributions
Qualified Charitable Distributions (“QCDs”) are distributions made from an Individual Retirement Account (“IRA”) directly to a qualified charity. QCDs are permitted for individuals age 70½ and older up to $111,000 in the calendar year 2026. A QCD may also count toward your Required Minimum Distribution (“RMD”) for the year, making it a valuable planning strategy for individuals who are already required to take distributions from their IRAs.
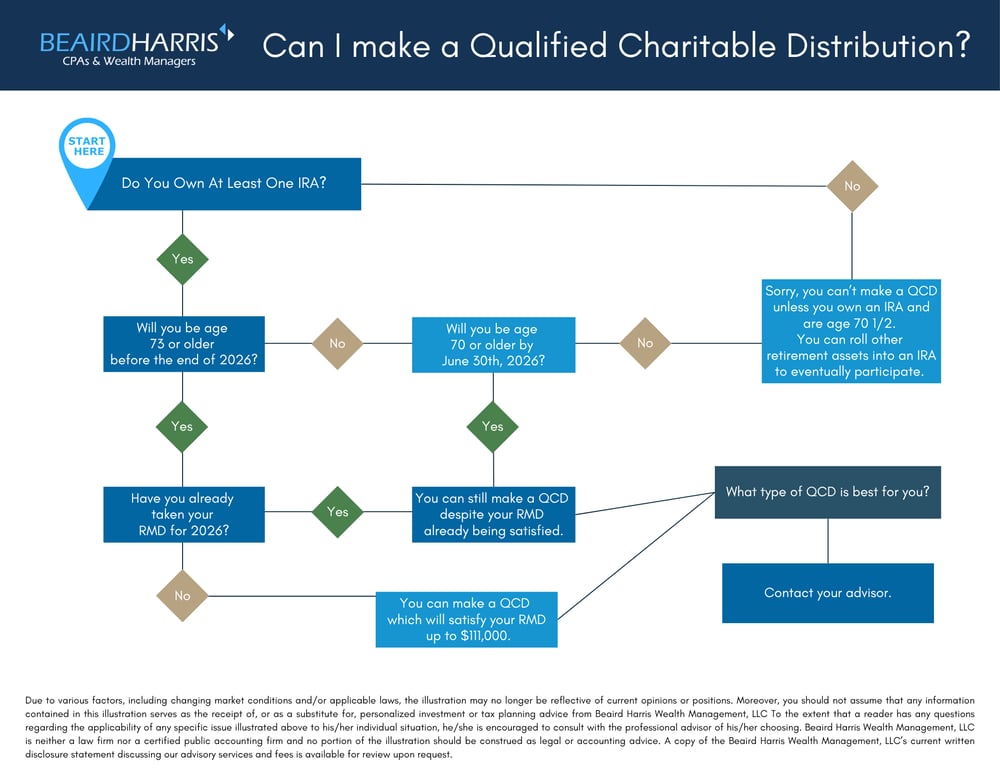
When processing a QCD, it is important to let your CPA know that the distribution was made directly to charity. Beginning in 2026, custodians may identify QCDs on Form 1099-R, but that reporting is optional for 2026, so you should still make sure your tax preparer is aware of the charitable distribution.
QCDs generally cannot be made to Donor-Advised Funds.
3. Donor-Advised Fund
A Donor-Advised Fund (“DAF”) is a charitable giving account established with a sponsoring charitable organization. You may be eligible for an immediate charitable deduction when you contribute assets to the DAF, while retaining the ability to recommend grants to qualified charities over time.
This strategy can be particularly useful when you own appreciated securities, such as stocks or mutual funds, that you have held for more than one year and would like to use for charitable giving. Once contributed to the DAF, the assets can generally be invested and remain in the account until you recommend grants to the charities of your choice.
DAFs may also be helpful in a year when your income is higher than usual, such as following the sale of a business, realization of a large capital gain or receipt of a significant bonus. Rather than making the same level of charitable gifts each year, you may choose to “bunch” several years of planned charitable contributions into the DAF in one year and potentially receive a larger charitable deduction that year. Grants can then be recommended from the DAF to your preferred charities over the following years.
4. New Charitable Deduction for Non-Itemizers
Beginning in 2026, taxpayers who do not itemize their deductions may still be eligible for a charitable deduction for certain cash contributions made to qualified organizations.
The deduction is generally limited to $1,000 for individual filers and $2,000 for married couples filing jointly, subject to applicable IRS requirements and limitations.
This new provision may provide an additional tax benefit for individuals whose charitable contributions would not otherwise result in an itemized deduction.
Ask your Wealth Manager if you are looking for ways to make a difference while incorporating charitable giving into your year-end tax and financial planning.
Required Minimum Distributions ("RMDs")
RMDs are required for everyone with IRAs and 401(k)-type accounts (but not defined benefit plans) for clients aged 73 or older; however, special rules apply to inherited IRAs.
- Inherited IRAs before 2020: Distribution requirements generally depend on the beneficiary and the rules that applied when the account was inherited.
- Inherited IRAs in 2020 or later: Most non-spouse beneficiaries are subject to a 10-year distribution rule. Depending on the circumstances, annual distributions may also be required during that 10-year period. Certain beneficiaries, including surviving spouses and other eligible designated beneficiaries, may qualify for different rules.
Ask your advisor about your plan for distributing your inherited IRA and if you should be taking an RMD this year. Also, if you have any IRAs not managed by Beaird Harris, including Inherited IRAs, you are responsible for fulfilling the IRS RMD requirement from those accounts.
Please Note: We are in the process of reaching out to all individuals who require an RMD and will be in touch soon if we haven't contacted you already; however, you are welcome to reach out to us directly to process your RMDs now if you would like.
_________________
Frequently Asked Questions
1. What is the deadline to process my year-end charitable gifts?
To allow adequate time for processing, please submit charitable gifting requests using these strategies by Friday, November 13th.
2. Why consider donating appreciated securities instead of cash?
If you donate appreciated securities that you have held for more than one year directly to a qualified charity, you may be able to avoid realizing capital gains on the appreciation while also receiving a charitable deduction based on the securities’ fair market value, subject to applicable IRS limitations.
3. Who can make a Qualified Charitable Distribution (QCD)?
If you’re age 70½ or older, you can give up to $111,000 per year directly from your IRA to a qualified charity. This distribution won’t count as taxable income, but you’ll need to tell your CPA it was a QCD so it can be properly reported on your tax return.
4. Is there a charitable deduction available if I do not itemize?
Yes. Beginning in 2026, taxpayers who do not itemize may still be eligible to deduct certain cash contributions made to qualified charitable organizations. The deduction is generally limited to $1,000 for individual filers and $2,000 for married couples filing jointly, subject to applicable IRS requirements and limitations.
5. What is a Donor-Advised Fund (DAF) and how does it work?
A DAF is like a charitable giving account you set up with your custodian. You get an immediate tax deduction when you contribute to it, and then you decide over time which charities receive grants. It’s especially useful if you have appreciated securities or unusually high income in a single year.
6. Who is required to take Required Minimum Distributions (RMDs)?
Generally, if you’re age 73 or older you must take an RMD from your IRA or 401(k)-type accounts each year. Inherited IRAs have their own special rules — some require annual withdrawals, others must be emptied within 10 years.
7. What should I do next if I’m interested in these strategies?
Reach out to your Wealth Manager. We can help you evaluate which strategies may be appropriate for your situation, coordinate charitable gifts before the year-end processing deadline and review your RMD requirements.